Inflation impact on small business: what rising prices really cost you and 5 ways to respond
In short
Inflation hurts small businesses by raising input, labor, rent and borrowing costs faster than most owners can raise prices, which squeezes profit margins and cash flow. The most effective responses are measuring your real cost increases, repricing deliberately, renegotiating with suppliers, cutting waste through better systems, and protecting cash and credit before you need them.
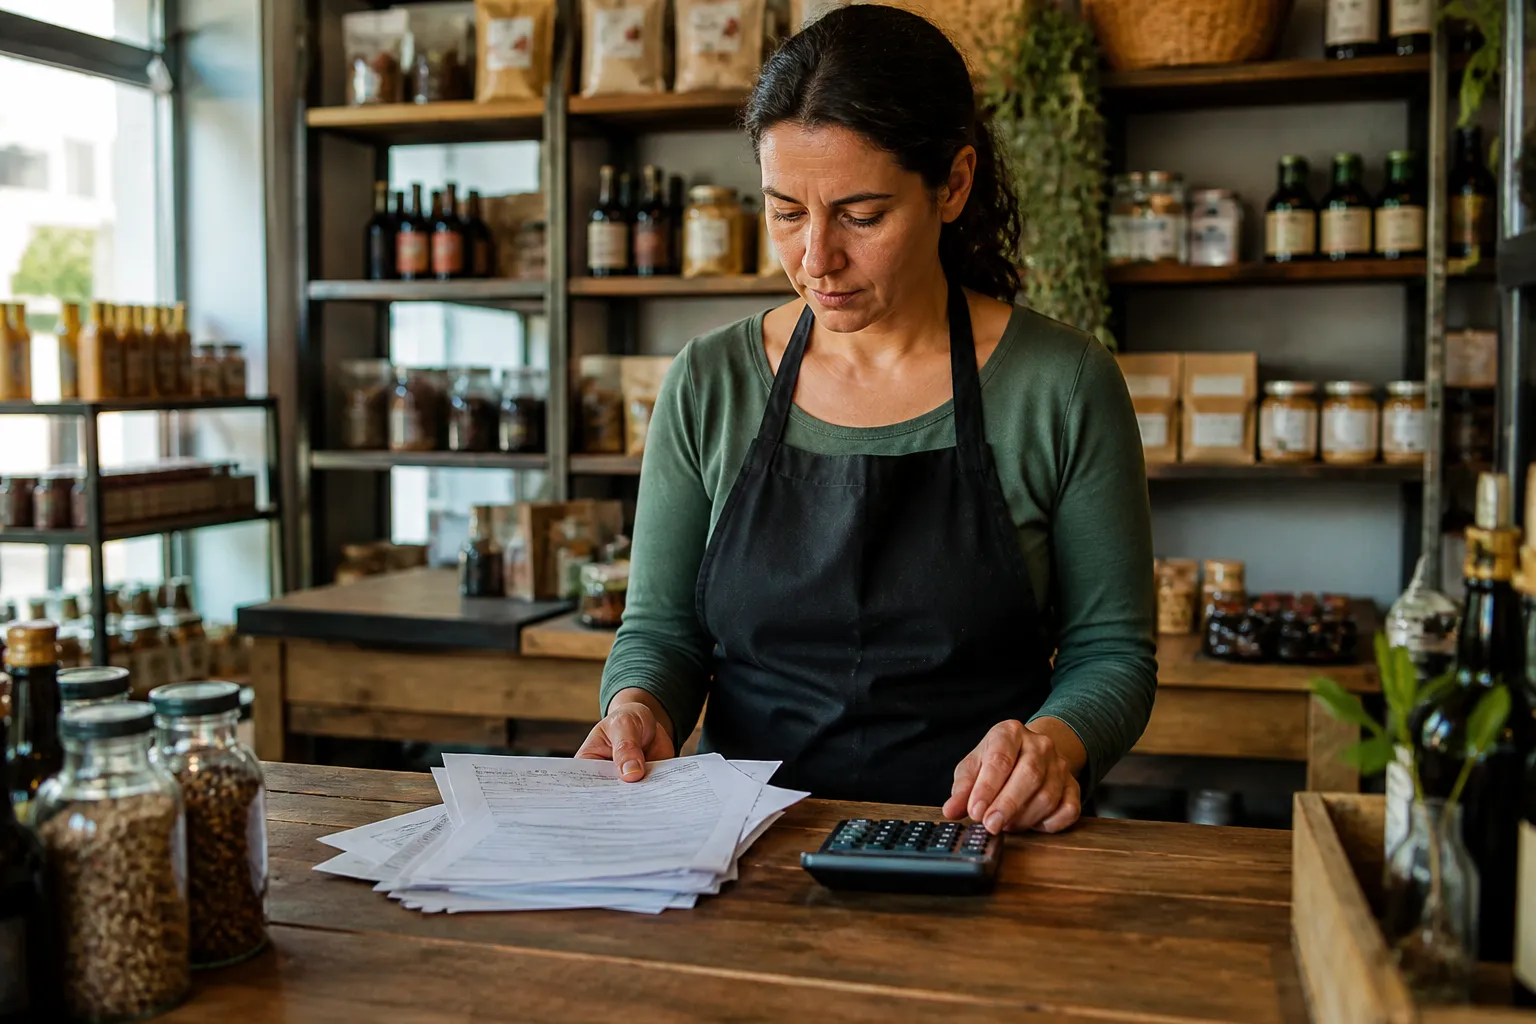
When prices rise across an economy, large companies feel it, but small businesses often feel it first and hardest. A café owner sees the coffee bean invoice jump. A small software startup sees its cloud bill and salary expectations climb. A repair shop finds that parts cost more and customers delay jobs. Over 11 years of reporting on startups and hardware makers, I have watched the same pattern repeat: inflation rarely arrives as one dramatic shock. It shows up as dozens of small increases that quietly erase a margin.
This guide explains how inflation affects small businesses, how to measure what it is costing you, and five concrete ways owners can respond without damaging customer relationships.
What is inflation and why does it hit small businesses harder?
Inflation is the general rise in prices across an economy over time, which means each unit of currency buys less than it did before. Governments usually track it with the Consumer Price Index (CPI), a measure of the average price change for a basket of common goods and services. A related figure, the Producer Price Index (PPI), tracks prices businesses pay for inputs, and it often moves before consumer prices do.
Small businesses are more exposed for a few structural reasons:
- Less buying power. A national chain can negotiate volume discounts or sign long contracts. A small retailer buying a few cases at a time usually pays the going rate.
- Thinner cash reserves. Many small firms operate with only a few weeks or months of cash on hand, so a rise in costs becomes a cash flow problem quickly.
- Weaker pricing power. Pricing power is the ability to raise prices without losing many customers. Small firms competing on price, or facing larger rivals, often have little of it.
- Higher borrowing costs. Central banks typically raise interest rates to fight inflation. Small businesses rely heavily on credit lines, cards and loans with variable rates, so financing gets more expensive at the worst moment.
Where does inflation show up in a small business's numbers?
Inflation does not hit every cost line equally. Understanding where the pressure comes from helps you decide what to fix first.
| Cost area | How inflation shows up | How fast it usually hits |
|---|---|---|
| Inventory and raw materials | Supplier price increases, surcharges, smaller order discounts | Fast, often within weeks |
| Wages | Staff ask for raises to keep up with living costs; hiring gets pricier | Medium, often at review time or when someone quits |
| Rent and utilities | Lease escalation clauses, higher energy bills | Slow for rent, fast for energy |
| Shipping and logistics | Fuel surcharges, higher carrier rates | Fast |
| Software and services | Subscription price increases, new paid tiers | Usually at renewal |
| Financing | Higher interest on variable loans and credit lines | Fast for variable debt |
There is also a revenue side. When household budgets tighten, customers trade down to cheaper options, buy less often, or delay big purchases. Business customers do the same by stretching payment terms. So inflation can squeeze a small firm from both directions at once: costs go up while demand softens.
Nominal versus real revenue
One trap is looking only at nominal revenue, the raw figure in your accounts. If sales rose 5 percent but prices in your sector rose 7 percent, your real revenue, meaning revenue adjusted for inflation, actually fell. You are selling less in real terms even though the top line looks healthier.
How can you tell how much inflation is costing your business?
Before reacting, measure. The national CPI figure is an average and may have little to do with your actual costs. A bakery can face far steeper increases than the headline number, while a consulting firm may face much smaller ones.
- Pull 12 months of invoices for your top 10 to 20 cost items. In most small businesses, a handful of items account for most spending.
- Compare unit prices, not totals. Track what you paid per kilo, per hour, per seat or per shipment then and now.
- Calculate your personal inflation rate by weighting each increase by how much you spend on that item.
- Check your gross margin trend. Gross margin is revenue minus the direct cost of what you sell, expressed as a percentage of revenue. If it has slipped several points, inflation is eating into profit.
As a practical estimate, an afternoon with a spreadsheet is enough for most businesses with a simple product line to get a usable picture. The goal is not precision to the decimal; it is knowing which costs are moving and by roughly how much.
What are 5 ways small business owners can respond to inflation?
1. Reprice deliberately instead of all at once
Many owners avoid raising prices until margins are badly damaged, then raise everything sharply. Customers tend to notice large jumps more than small, regular, explained adjustments. Better approaches include:
- Raising prices on items where your costs rose most, rather than applying one flat increase.
- Protecting a few visible, frequently bought items that customers use to judge whether you are expensive.
- Adding tiers, such as a basic and a premium option, so price sensitive customers still have a choice.
- Explaining increases briefly and honestly. A short note saying supplier costs rose is usually received better than silence.
For service businesses and startups selling subscriptions, consider building annual price reviews into contracts so increases are expected rather than surprising.
2. Renegotiate with suppliers and review your vendor list
Suppliers are dealing with inflation too, but there is often room to talk. Ask about discounts for paying early, committing to larger orders, or signing a longer agreement at a fixed price. Get quotes from at least two alternatives for your biggest cost items, even if you do not switch. Knowing the market rate strengthens your position.
Small firms can also pool purchasing through trade associations or buying groups to access volume pricing they could not get alone.
3. Cut waste with better systems and technology
Inflation makes inefficiency more expensive. This is where modest technology spending can pay off:
- Inventory software that tracks stock levels can reduce overordering and spoilage.
- Energy monitoring and simple upgrades such as LED lighting or smart thermostats can trim utility bills.
- Subscription audits often reveal unused software seats. Many small companies pay for tools nobody has opened in months.
- Automation of repetitive tasks such as invoicing, scheduling and payment reminders frees staff time without new hires.
Be careful not to replace one cost with another. Any new tool should have a clear payback period, ideally within a year for a small business under pressure.
4. Protect cash flow and secure credit early
Cash flow is the timing of money coming in and going out. During inflation, slow paying customers effectively pay you less, because the money they owe loses value while you wait. Tighten your terms where you can, send invoices promptly, and offer a small discount for early payment if it makes sense.
On the debt side, review any variable rate loans and consider whether fixing a rate is worth the cost. If you might need a credit line, apply while your financials still look strong. Lenders become more cautious as conditions tighten, and it is much harder to borrow once you are already in trouble.
5. Focus on value and your most profitable customers
Not all revenue is equally useful. Look at which products, services and customers produce the best margin after costs. Inflation is a good moment to drop or reprice offerings that barely break even, and to put more effort into the ones that carry the business.
Retaining existing customers is usually cheaper than winning new ones. Loyalty programs, better service, and clear communication about quality help customers justify paying a little more to you instead of switching to a cheaper rival.
Which response should you prioritize first?
The right order depends on your business model. This comparison is a practical starting point, not a fixed rule.
| Business type | Main inflation pressure | Strongest first response |
|---|---|---|
| Retail and food service | Inventory, ingredients, energy | Supplier negotiation and selective repricing |
| Software and tech startups | Salaries, cloud and tool costs | Subscription audit and annual price reviews |
| Trades and repair | Parts, fuel, labor | Repricing quotes and tightening payment terms |
| Professional services | Wages, rent | Value based pricing and client focus |
| Ecommerce sellers | Shipping, product costs, ad prices | Shipping strategy and margin review by product |
What mistakes should owners avoid during inflation?
- Waiting too long to act. Small, early adjustments are easier on customers and on cash flow than emergency changes later.
- Cutting quality quietly. Shrinking portions or swapping cheaper materials without telling customers can damage trust more than an honest price rise.
- Ignoring staff. Employees face the same rising costs. Losing a trained person and hiring a replacement can cost more than a reasonable raise.
- Overreacting to headlines. National inflation figures are averages. Base decisions on your own cost data.
- Locking in bad deals out of fear. A fixed price contract only helps if the price is fair and the volume matches your real needs.
Inflation does not have to break a small business, but it does punish owners who are not watching their numbers closely.
The practical takeaway is simple: measure your real cost increases, adjust prices thoughtfully, push back on suppliers, remove waste, and protect your cash. Owners who treat inflation as an ongoing management task, rather than a one time crisis, are usually the ones still standing when prices settle.
Frequently asked questions
Written by
Priya NatarajanSenior technology reporter, 11 years covering consumer hardware and startups
Priya Natarajan has reported on personal computing, AI products and early stage funding since 2013, starting at a regional business daily before moving to online tech news. She has covered more than 150 startup funding rounds and tested over 80 laptops and desktops for hands on reviews. She holds a master's degree in journalism and a bachelor's degree in computer science.